All Categories
Featured


How to Negotiate Credit Card Balances in 2026
Table of Contents
Have you ever took a look at your credit card costs and wondered where all those charges originated from? Or found yourself swiping your charge card for a purchase before you've had a possibility to think of whether you truly wished to obtain cash to spend for it? Do not feel dissuaded there are ways to get a much better hang on your credit card use.
The guidelines are created to help you enhance the options you make with your charge card especially when you change the rule to live by to fit your individual financial circumstance. We have actually developed a worksheet to help you produce and follow your own cash guidelines to live by. Use the worksheet to: Discover locations where you may utilize your charge card less often Choose an objective for managing your credit card usage Produce a rule to live by for how you wish to use your charge card Make a commitment to yourself to act upon your objective Taking a close appearance at your small charge card purchases is one location to start to help acquire control over your charge card costs.
Utilizing the worksheet to make a note of your objective will likewise help you adhere to it. Just like lane markers on a highway, your cash guidelines to live by are guidelines that keep you moving in the right direction. You might have to speed some things up, decrease others, or change lanes from time to time, but your guidelines to live by can help you reach your monetary destination.
Reducing Household Debt with 2026 Management ToolsInformation from FICO and TransUnion point to 3 primary forces forming 2026 credit behavior across all income levels: a little lower typical scores, elevated credit usage, and stablebut progressively influentialcredit delinquencies. At the very same time, BHG Financial data reveals a mixed picture: many consumers report feeling economically positive, yet a meaningful share are still browsing capital difficulties and rising debt responsibilities.
Increased reliance on revolving credit and the return of trainee loan delinquencies to credit reports in 2025 have both contributed to the shift. Generational patterns include crucial context. Younger customers, especially Gen Z, are opening credit cards at greater rates than previous generations and using them more actively. This suggests earlier engagement with creditbut likewise increases the probability of higher balances and score volatility without recognized repayment habits or long credit histories.
Complete Debt Consolidation Reviews for the New Year
Amongst the biggest aspects influencing ratings, credit usage stands out. This metric procedures just how much of your available credit you're usinghigher usage normally signals higher risk to loan providers and can reduce ratings. FICO information show that average charge card balances and usage rates have actually climbed up considerably since 2020, surpassing pre-pandemic levels.
While this usage level is above the commonly suggested limit (often listed below 30%), the current plateau recommends that many customers are handling greater balances without a matching spike in payment tension. This shows relative stabilitybut at a higher level of continuous debt. While credit delinquencies remain comparatively steady, indications of financial strain are ending up being more noticeable.
Federal Reserve data support this pattern, revealing steadiness across credit card and auto loan segments. Threat, however, is not uniformly dispersed. It is more focused amongst debtors managing greater balances, multiple accounts, or inconsistent money circulation. BHG Financial's research study highlights this detach: 56% of participants say they feel financially comfortable or rich, yet 36% live paycheck to paycheckincluding 24% of high earners making $100,000 or more each year.
Finding 2026 Financial Hardship Assistance
These patterns highlight an essential style: monetary stability and financial stress can coexist. Financial intricacy is increasing across earnings levels, however especially amongst high earners, who are browsing more obligations than ever. Many belong to the "sandwich generation," supporting kids and aging moms and dads while pursuing their own objectives. This multi-income, multi-responsibility truth means financial obligation is less about overspending and more about handling contending top priorities.
Reducing Household Debt with 2026 Management ToolsSo it makes sense that this segment of the population might count on obtaining to keep their grip or manage capital. In this context, financial obligation is not naturally negative. Rather, it can be a tool that supports long-lasting monetary healthas long as it's structured well and coupled with a clear repayment strategy.
We're sorry, however we were not able to authorize your demand. Please call us at 800-433-9196 and offer recommendation number SWAF-18. d61c2117.1785214553. fa1915a7. We excuse any hassle. 0915-82LR
Credit cards have become vital to contemporary life, enabling us to manage requirements we can not purchase outright. Credit can be a double-edged sword.

Latest Posts

2026 Guide to Successful Debt Relief
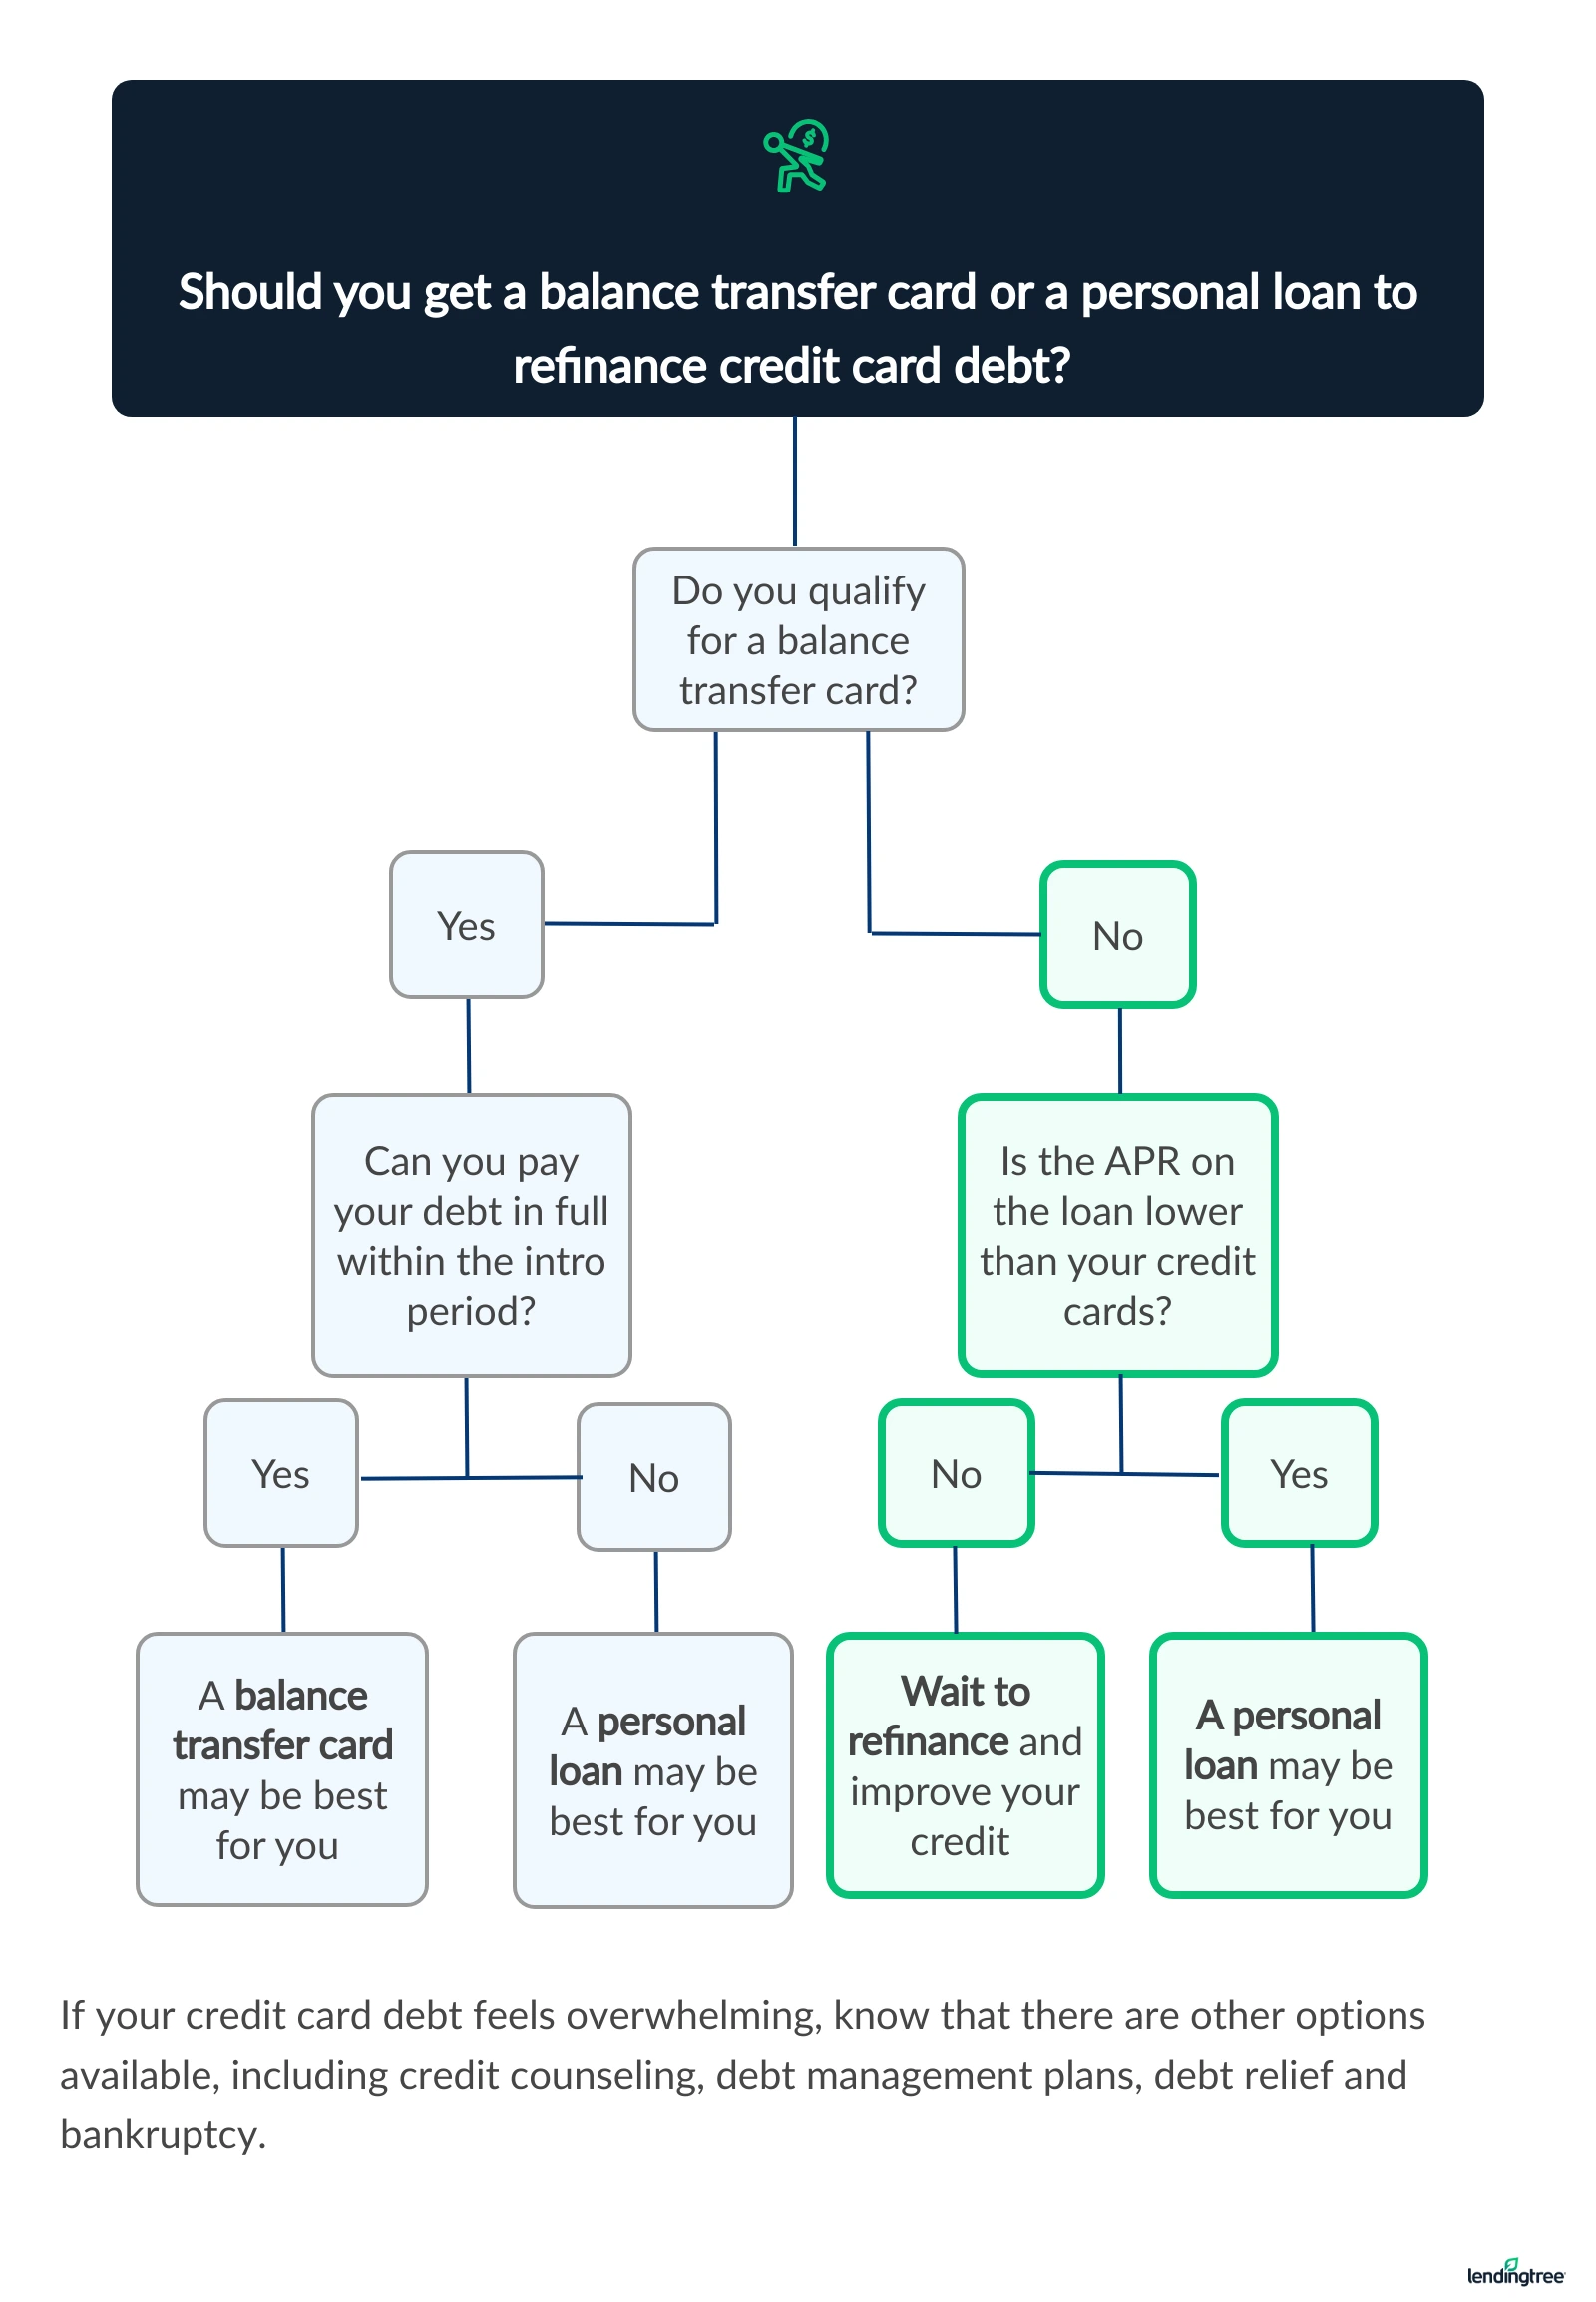
Steps to Lower Credit Card Debt in 2026
Smart Tips to Handle 2026 Financial Stress