All Categories
Featured

How to Eliminate High-Interest Debt in 2026
Home loans aren't simple to knock out overnight. It's an honorable financial goal to prioritize paying off your mortgage early and owning your home outright. Here are a couple strategies you can talk about with your bank to see if they make good sense. Recasting allows you to make a lump-sum payment towards your principal and ask your loan provider to re-amortize the loan.
Refinancing might make sense if rates fall far enough in 2026. Either strategy can assist release up monthly money flow, which you can put straight back into primary paydown or other monetary objectives.
That's where a non-profit credit counseling company can help. (NFCC) offer: Free or affordable one-on-one guidanceHelp producing customized debt reward plansNegotiating assistance with lendersAccess to structured Financial obligation Management Plans (DMPs), where you make a single regular monthly payment and the agency pays your creditors directlyHonestly, I have actually spoken with individuals that work for these non-profits and they are life-savers.

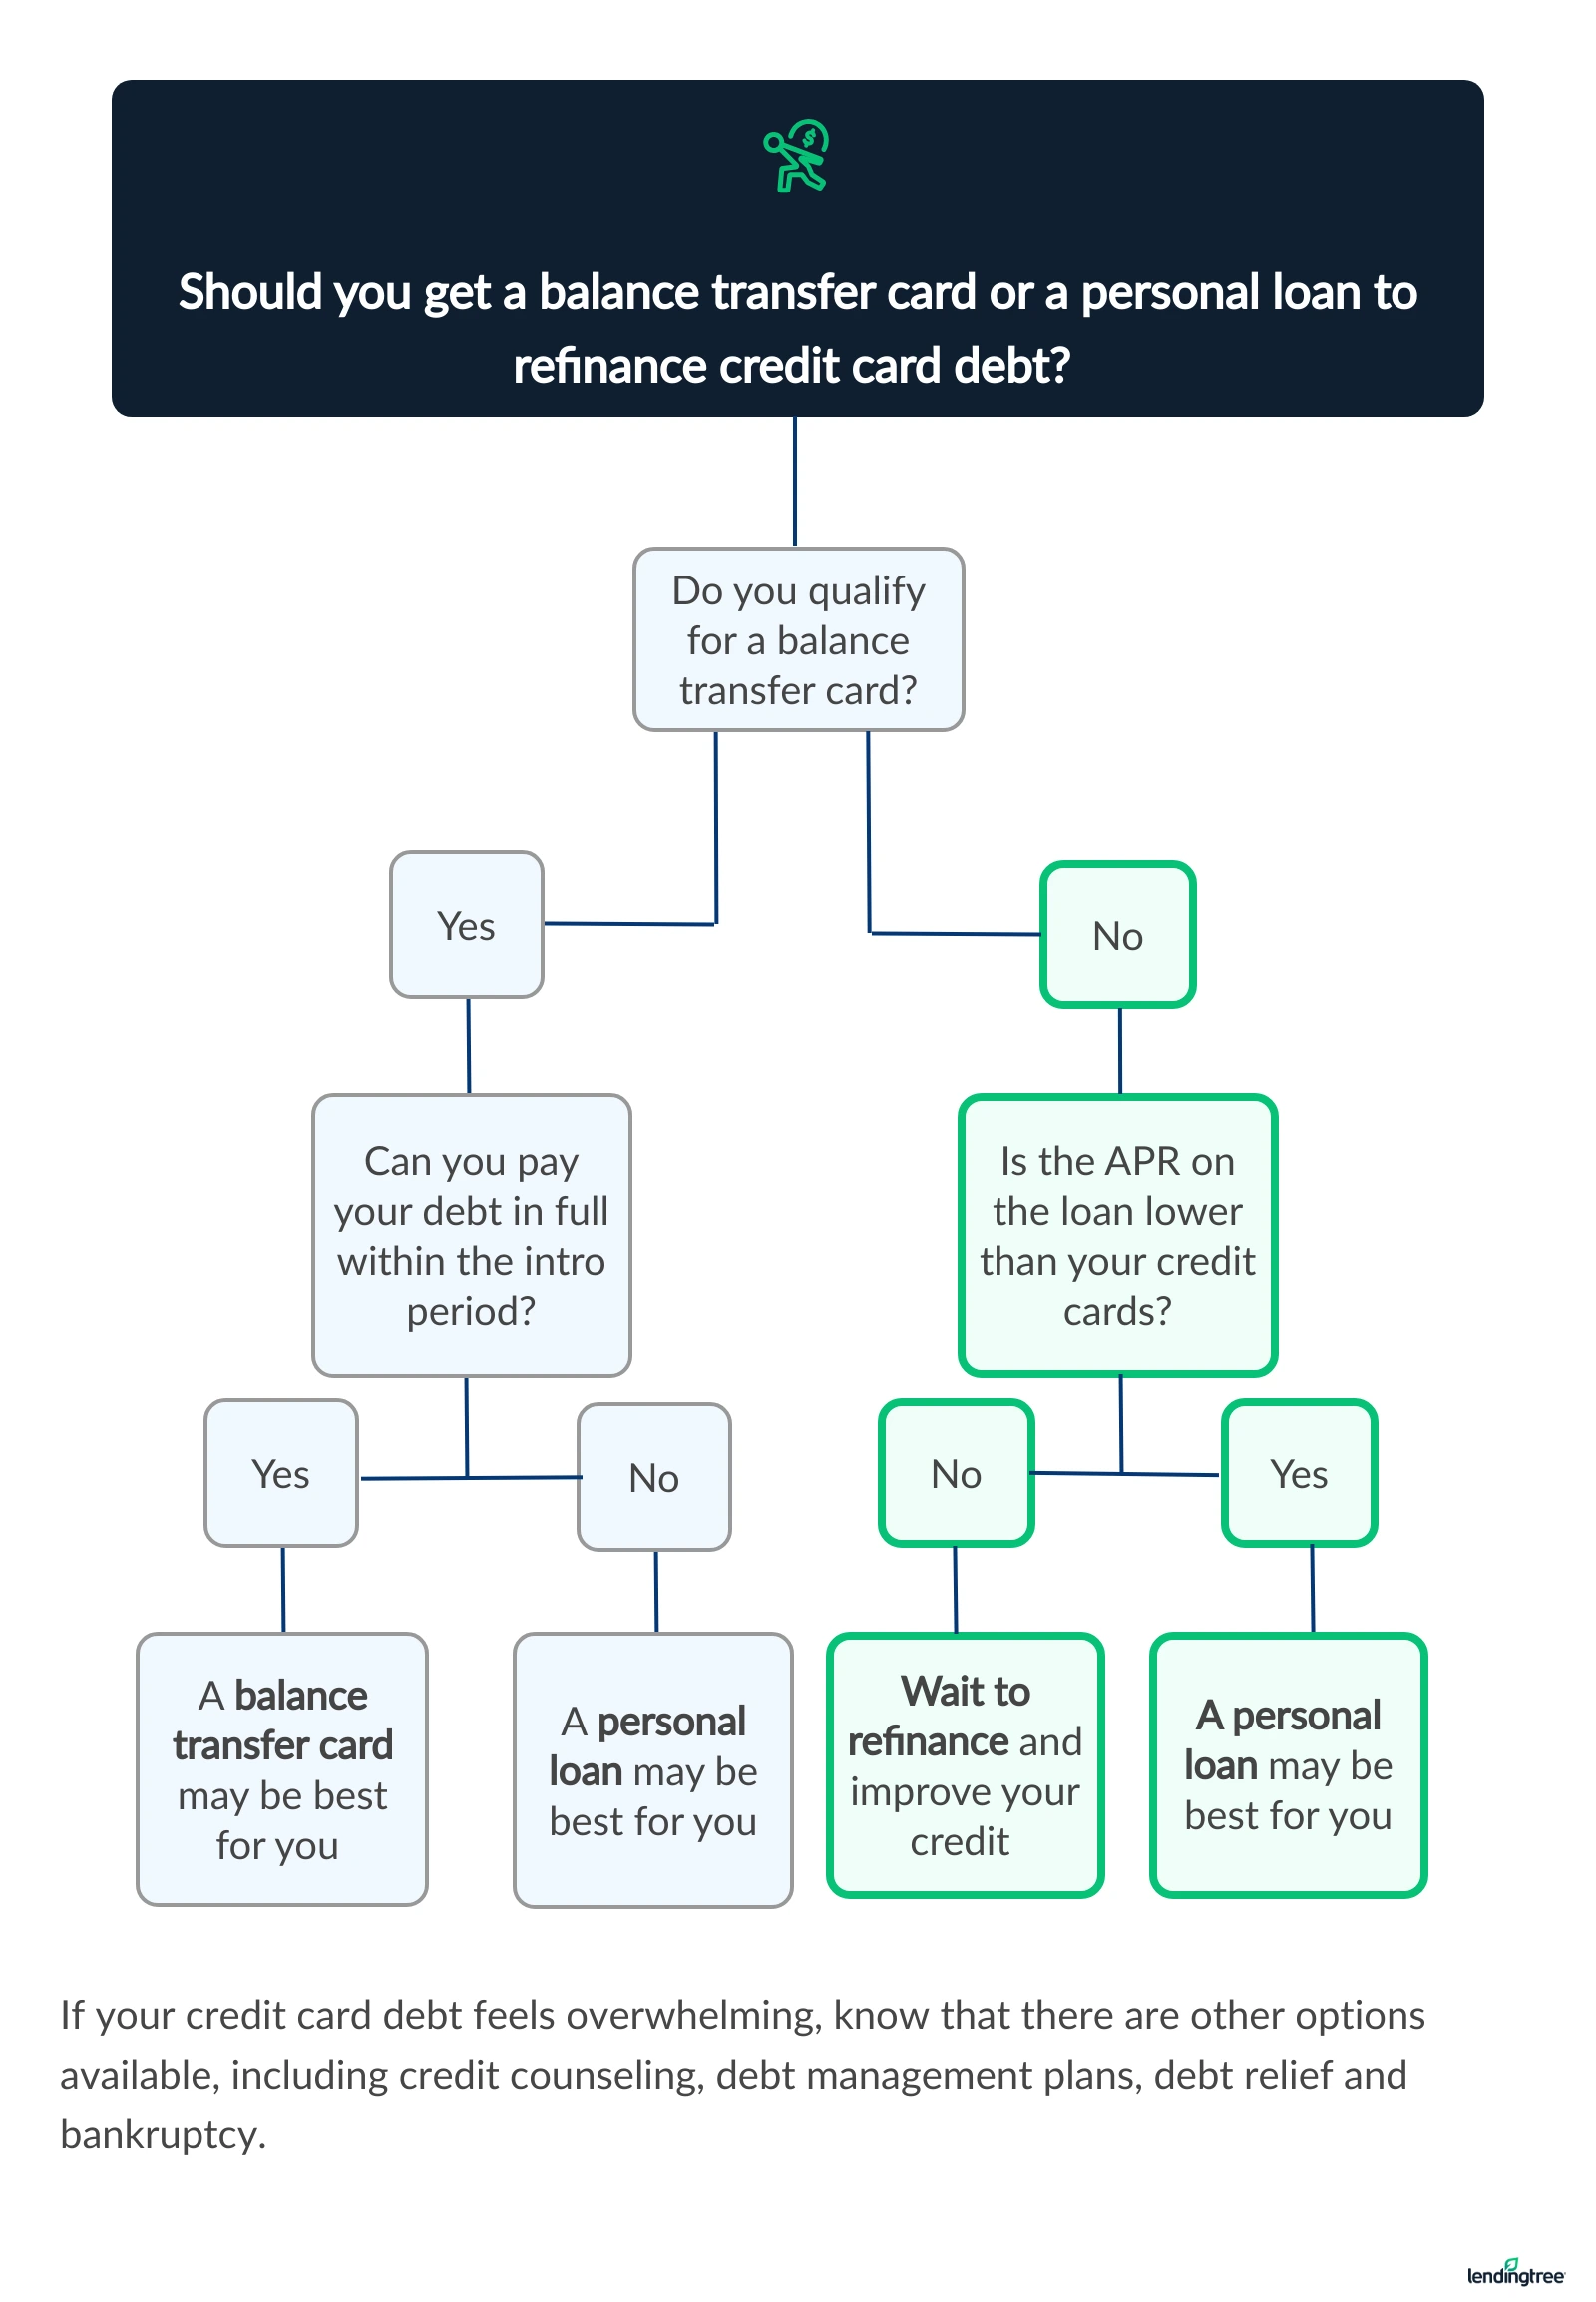
There's no magic trick to entirely eliminate your debt. It takes tough work, conserving money, and making consistent payments. Others-- like balance transfer cards-- give you a head start by dropping interest rates to 0% for a duration and letting you put every dollar towards progress.
Do government financial obligation relief programs exist? Yes, there are a number of programs available to people with financial issues who require assistance. These programs consist of: IRS Clean slate programIncome-driven trainee loan repaymentStudent loan disability dischargePublic service loan forgivenessIf you qualify, these programs can help you get out from under unaffordable financial obligation. Nevertheless, there are no federal government debt relief programs for charge card balances.
When to Walk Away From a Bad Settlement OfferFinding Financial Hardship Help in 2026
Can the government aid with your financial obligation? There are a couple of different ways the federal government could help make your debt more manageable.
Take the time to examine the government financial obligation relief options detailed listed below to see if you may certify.
IRS debt relief options consist of: Pay in time: You can use to the IRS to establish an installment payment strategy instead of having to pay at one time: This is a worked out settlement to pay less than the total you oweCurrently not collectible: If the IRS determines you can not pay your financial obligation at this time, they might concur to postpone collection till you are much better able toPenalty abatement: The internal revenue service may accept waive particular penalties if you took steps to comply with the guidelines but didn't make payments due to factors beyond your control.
If you can not afford to pay your state income taxes, connect to your state's department of tax. Income-driven repayment plans are designed to make your trainee loan payments more inexpensive. They do this by basing your month-to-month payments on how much money you make. There are 4 kinds of income-driven student loan repayment plans: Minimize a Prized Possession Education (CONSERVE): This was previously the REPAYE Plan.
Forgives remaining debt after 20 to 25 years. Pay As You Earn Repayment Plan (PAYE Strategy): Limits repayment to 10% of discretionary earnings. Forgives staying debt after 20 years. Income-Based Repayment Plan (IBR Strategy): Limitations repayment to 10% or 15% of discretionary income. Forgives staying debt after 20 to 25 years.
Reducing Unsecured Debt in 2026
Forgives staying debt after 25 years. Keep in mind that these plans are subject to change over time. Even for those who certify, these plans are not automated.
How to Benchmark Debt Against Current RatesCredentials for these programs depends on your monetary circumstances, what type of loan you have and when you obtained it., you might be able to get your loans discharged.

Latest Posts

2026 Guide to Successful Debt Relief
Steps to Lower Credit Card Debt in 2026
Smart Tips to Handle 2026 Financial Stress