All Categories
Featured


Evaluating the Top 2026 Debt Relief Plans
Table of Contents
Here's a breakdown of a few of the most popular ones to consider: This method begins by listing your financial obligations from tiniest to largest. Make minimum payments on all your cards while carrying any extra funds towards the tiniest balance. Once you pay off the tiniest debt, you'll carry on to the next tiniest and gain momentum with each triumph.
It takes longer to pay off high-interest debts. Those focused on fast wins and remaining motivated Focus on paying off the financial obligation with the greatest interest rate.
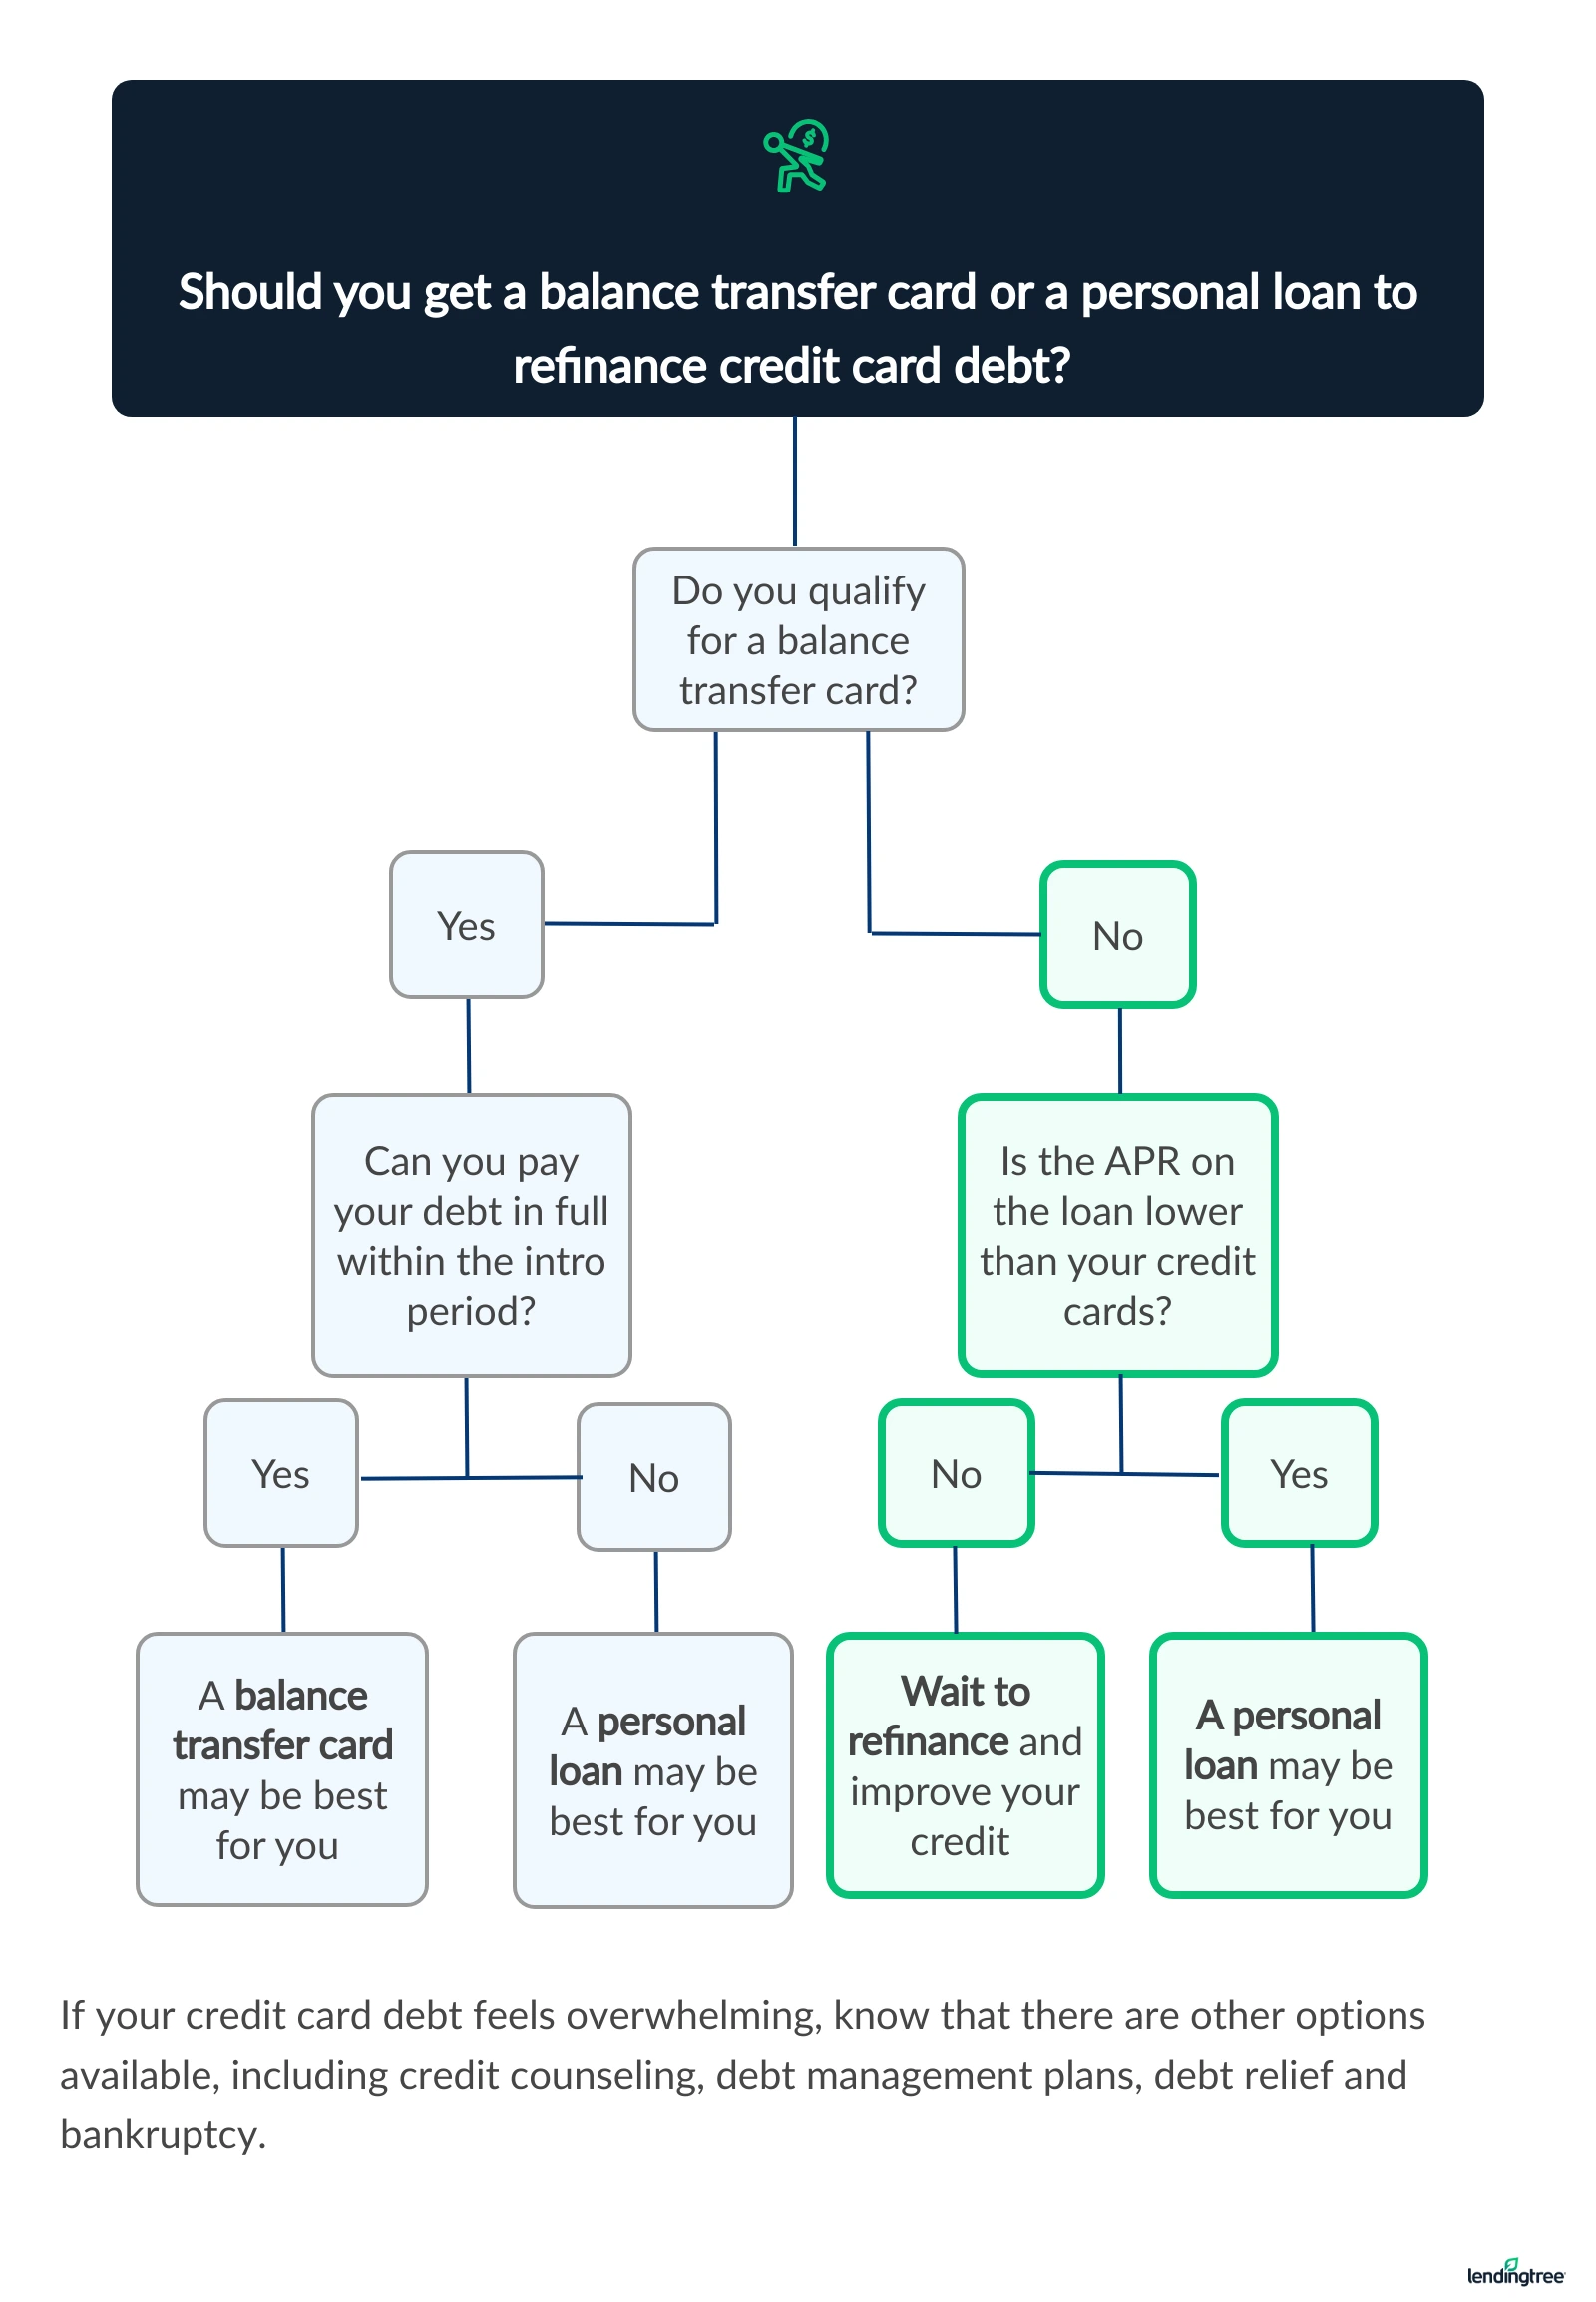
Those concentrated on minimizing overall interest paid and quicker total debt reduction. This technique integrates your card debts into a single loan with a lower rates of interest. It can simplify your payments and conserve you cash on interest charges. There are two main options: A individual loan is not backed by security, and approval depends on your creditworthiness.
It needs good credit to certify, and interest rates are usually higher than those for guaranteed loans. Those with great credit who prefer the simpleness of a single payment.
This alternative may offer lower rate of interest than credit cards. Consolidating several financial obligations can also streamline monthly payments. Unsecured loans usually require great credit to certify. A home equity loan puts your home at threat if you stop working to pay back. This strategy is ideal for individuals with excellent credit who prefer the simplicity of a single regular monthly loan payment.
Ways to Settle Your Debt in 2026
However, numerous other extra tactics can lower credit card financial obligation tension: While the minimum payment keeps your account in excellent standing, it will not considerably minimize your debt. Paying even a little extra each month will lower the amount you owe much faster. If possible, established automated payments above the minimum to make the process easier.
This can create a vicious circle of debt that's hard to get away. Think about keeping a few cards locked away or momentarily reducing your credit line as you restore healthy spending practices. Producing a comprehensive spending plan helps you track where your money goes, revealing areas where you can cut down. This will maximize more funds to eliminate your debt.
A credit therapy course can offer important assistance if you find it challenging to handle several credit cards properly. If you're struggling, contact the credit card provider and explain your circumstance.
Wasatch Peaks Credit Union uses private, no-cost, individualized debt management counseling. These services can be valuable if managing debt is frustrating or you need professional assistance creating a payment technique. One of the fastest ways to take on debt is to make more cash. Consider taking on a side gig, offering unused items, or requesting a raise at your existing task.
You've paid off your credit cardnow what? Now that you have actually paid off your credit card, you might wonder about your next actions.
Professional Analysis of Debt Relief Trends
Even if you don't plan on utilizing the card frequently, keeping it open for emergency situation expenses could be useful.
Just be conscious that it can briefly reduce your credit rating. You can utilize the funds to pay down other debts faster.
Redirecting credit card payments to cost savings can supplement your funds for getaways, big purchases, or emergency situation funds. Credit bureaus monitor this metric to evaluate your credit usage.
How to Get 2026 Financial Hardship Relief
If you're having a hard time to remain within your budget, think about designating your credit card for emergencies just. Comprehending how long to pay off a credit card can assist you make the essential way of life changes to reach your objective.
Even small modifications over time can create room in your spending plan for financial obligation payment. Be careful of services that guarantee to rapidly erase your financial obligation or drastically settle it for a portion of what you owe.
When used properly, credit cards can considerably enhance your credit score. Managing credit card financial obligation can be a considerable monetary difficulty.

Devoting yourself to a technique is the crucial to leaving charge card financial obligation quickly. When you adhere to your goal, your commitment equates into an overarching way of life where you no longer need to concern yourself with tackling your charge card payments each month. We can't make your monthly charge card payments for you (actually, we kind of can with an individual loan), but we can show you how to leave credit card debtfast! Keep reading to learn more about the leading 4 methods to pay off your charge card in the quickest manner possible.
If you have a $350 balance on a credit card with a 21-percent yearly rate of interest, and you make a minimum payment of only $20 each month, it will take you 22 months to pay it off. That's nearly two years. If you double your payment to $40, you'll have the card paid off in only 10 months.
How to Lower Credit Card Debt in 2026
This technique becomes even more valuable when you use it to even bigger balances. State you are making the minimum $90 payment on a card with a $2,750 balance and a 21 percent interest rate: You'll discover yourself paying for the next 45 months (or 3.75 years). If you double the regular monthly payment, you'll be out of debt in just 18 months (1.5 years).

Latest Posts

2026 Guide to Successful Debt Relief
Steps to Lower Credit Card Debt in 2026
Smart Tips to Handle 2026 Financial Stress