All Categories
Featured

Comprehensive Debt Management Reviews to Watch
Table of Contents
Many clients are mainly pleased with MMI's service. Some unfavorable evaluations complained of transparency and account setup problems and regreted the procedure as time-consuming.: MMI appears similarly focused on assisting customers get out of debt, while educating them on the subject so they do not return.
Is the 24-7 client service accessibility and service in Spanish. If you've got debt-relief issues, this is an excellent location to find answers.: A+: $36: Plenty of instructional material offered online, consisting of complimentary webinars, budget plan pointers and online chats. Counselors have won awards for their treatment of customers.
Greenpath has 60 branch workplaces in 16 states if you prefer in-person counseling.: Company's website could do a much better job specifying financial obligation management programs. The month-to-month service charge of $36 is above average, and some clients get charged for credit reports. Customers were significant fans of the basic registration procedure and direct, monthly payments.
Is 2026 a Strategic Time for Credit Relief?: GreenPath has a worthy goal "directing clients toward accomplishing monetary dreams" and GreenPath University can go a long way in getting them there. Credit therapists are strong and understanding, and online resources (podcasts, webinars, calculators) abound. Greater than typical charges are GreenPaths greatest downside.: A+ Based on budget, $40 average, $70 optimum: The company's site says they typically decrease the rate of interest on debt to somewhere between 0% and 11%.
Navigating Financial Hardship Assistance for Families
The website lists complimentary seminars by date and time, making it simple to schedule a knowing experience.: Consolidated Credit's month-to-month fees are higher than the industry average. If the rate is expensive, you can still make the most of its free, monetary education center. This is an online resource that includes webinars, workshops, infographics, and credit building guides.
The personnel reveals compassion and understanding regarding your financial issues. Nevertheless, some customers were dissatisfied with their payment schedules and felt Consolidated Credit had actually not been in advance concerning costs.: Consolidated Credit offers legitimate financial obligation management services and has actually helped countless customers in leaving debt. Online resources are in-depth and appealing, however monthly charges are greater than average.
: A+: $30: Counselors typical 14 years of work with Cambridge, which is phenomenal in this industry. Cambridge's site says to expect rate of interest decreases on charge card financial obligation from 22% down to 8%, which they state will conserve you $150 a month. There is an abundance of posts, manuals and newsletters that educate customers on a wide variety of subjects.
Tips to Reduce Credit Card Debt in 2026
four of those days. Their articles have no dates, making it difficult to inform how relevant they are. Easy to reach, transparent, and courteous were how consumers described the engaging personnel and basic enrollment process. On the contrary, others found the procedure confusing, mentioning a lack of insight concerning payment schedule and credit history impact.
Though debt management is their primary focus, they also have real estate and student loan departments. Evaluation sites offer Cambridge client service high marks, which is excellent since they aren't there on weekends or late during the night. Still, an excellent option for financial obligation management. Financial obligation management programs (or DMPs) are among three popular services for monetary problems debt combination loans and financial obligation settlement are the others and easily the least understood.
It tries to decrease the interest paid on that debt to around 8%, often lower. The month-to-month payment is sent out to a not-for-profit credit therapy company, dispersing an agreed-upon amount to each card business. The goal of financial obligation management programs is to be the go-between for customers looking for a method to eliminate debt and charge card business who desire to get paid what they are owed.
How to Erase High-Interest Debt in 2026That normally involves a considerable concession on rates of interest by the card companies in return for the guarantee that the customer will pay off the debt in a 3-5 year period. Financial obligation management programs are not a loan. Those originated from banks or cooperative credit union. Debt management programs do not promise to lower the amount owed.
Ways to Eliminate Credit Card Debt
Debt management programs are an issue solver for consumers who require counseling on budgeting and handling money. They inform customers on how to cut expenses or raise income so they can slowly get rid of debt. The most convenient way to enlist in a debt management program is to call a not-for-profit credit counseling company, preferably licensed by the National Foundation for Credit Counseling (NFCC).

Latest Posts

2026 Guide to Successful Debt Relief
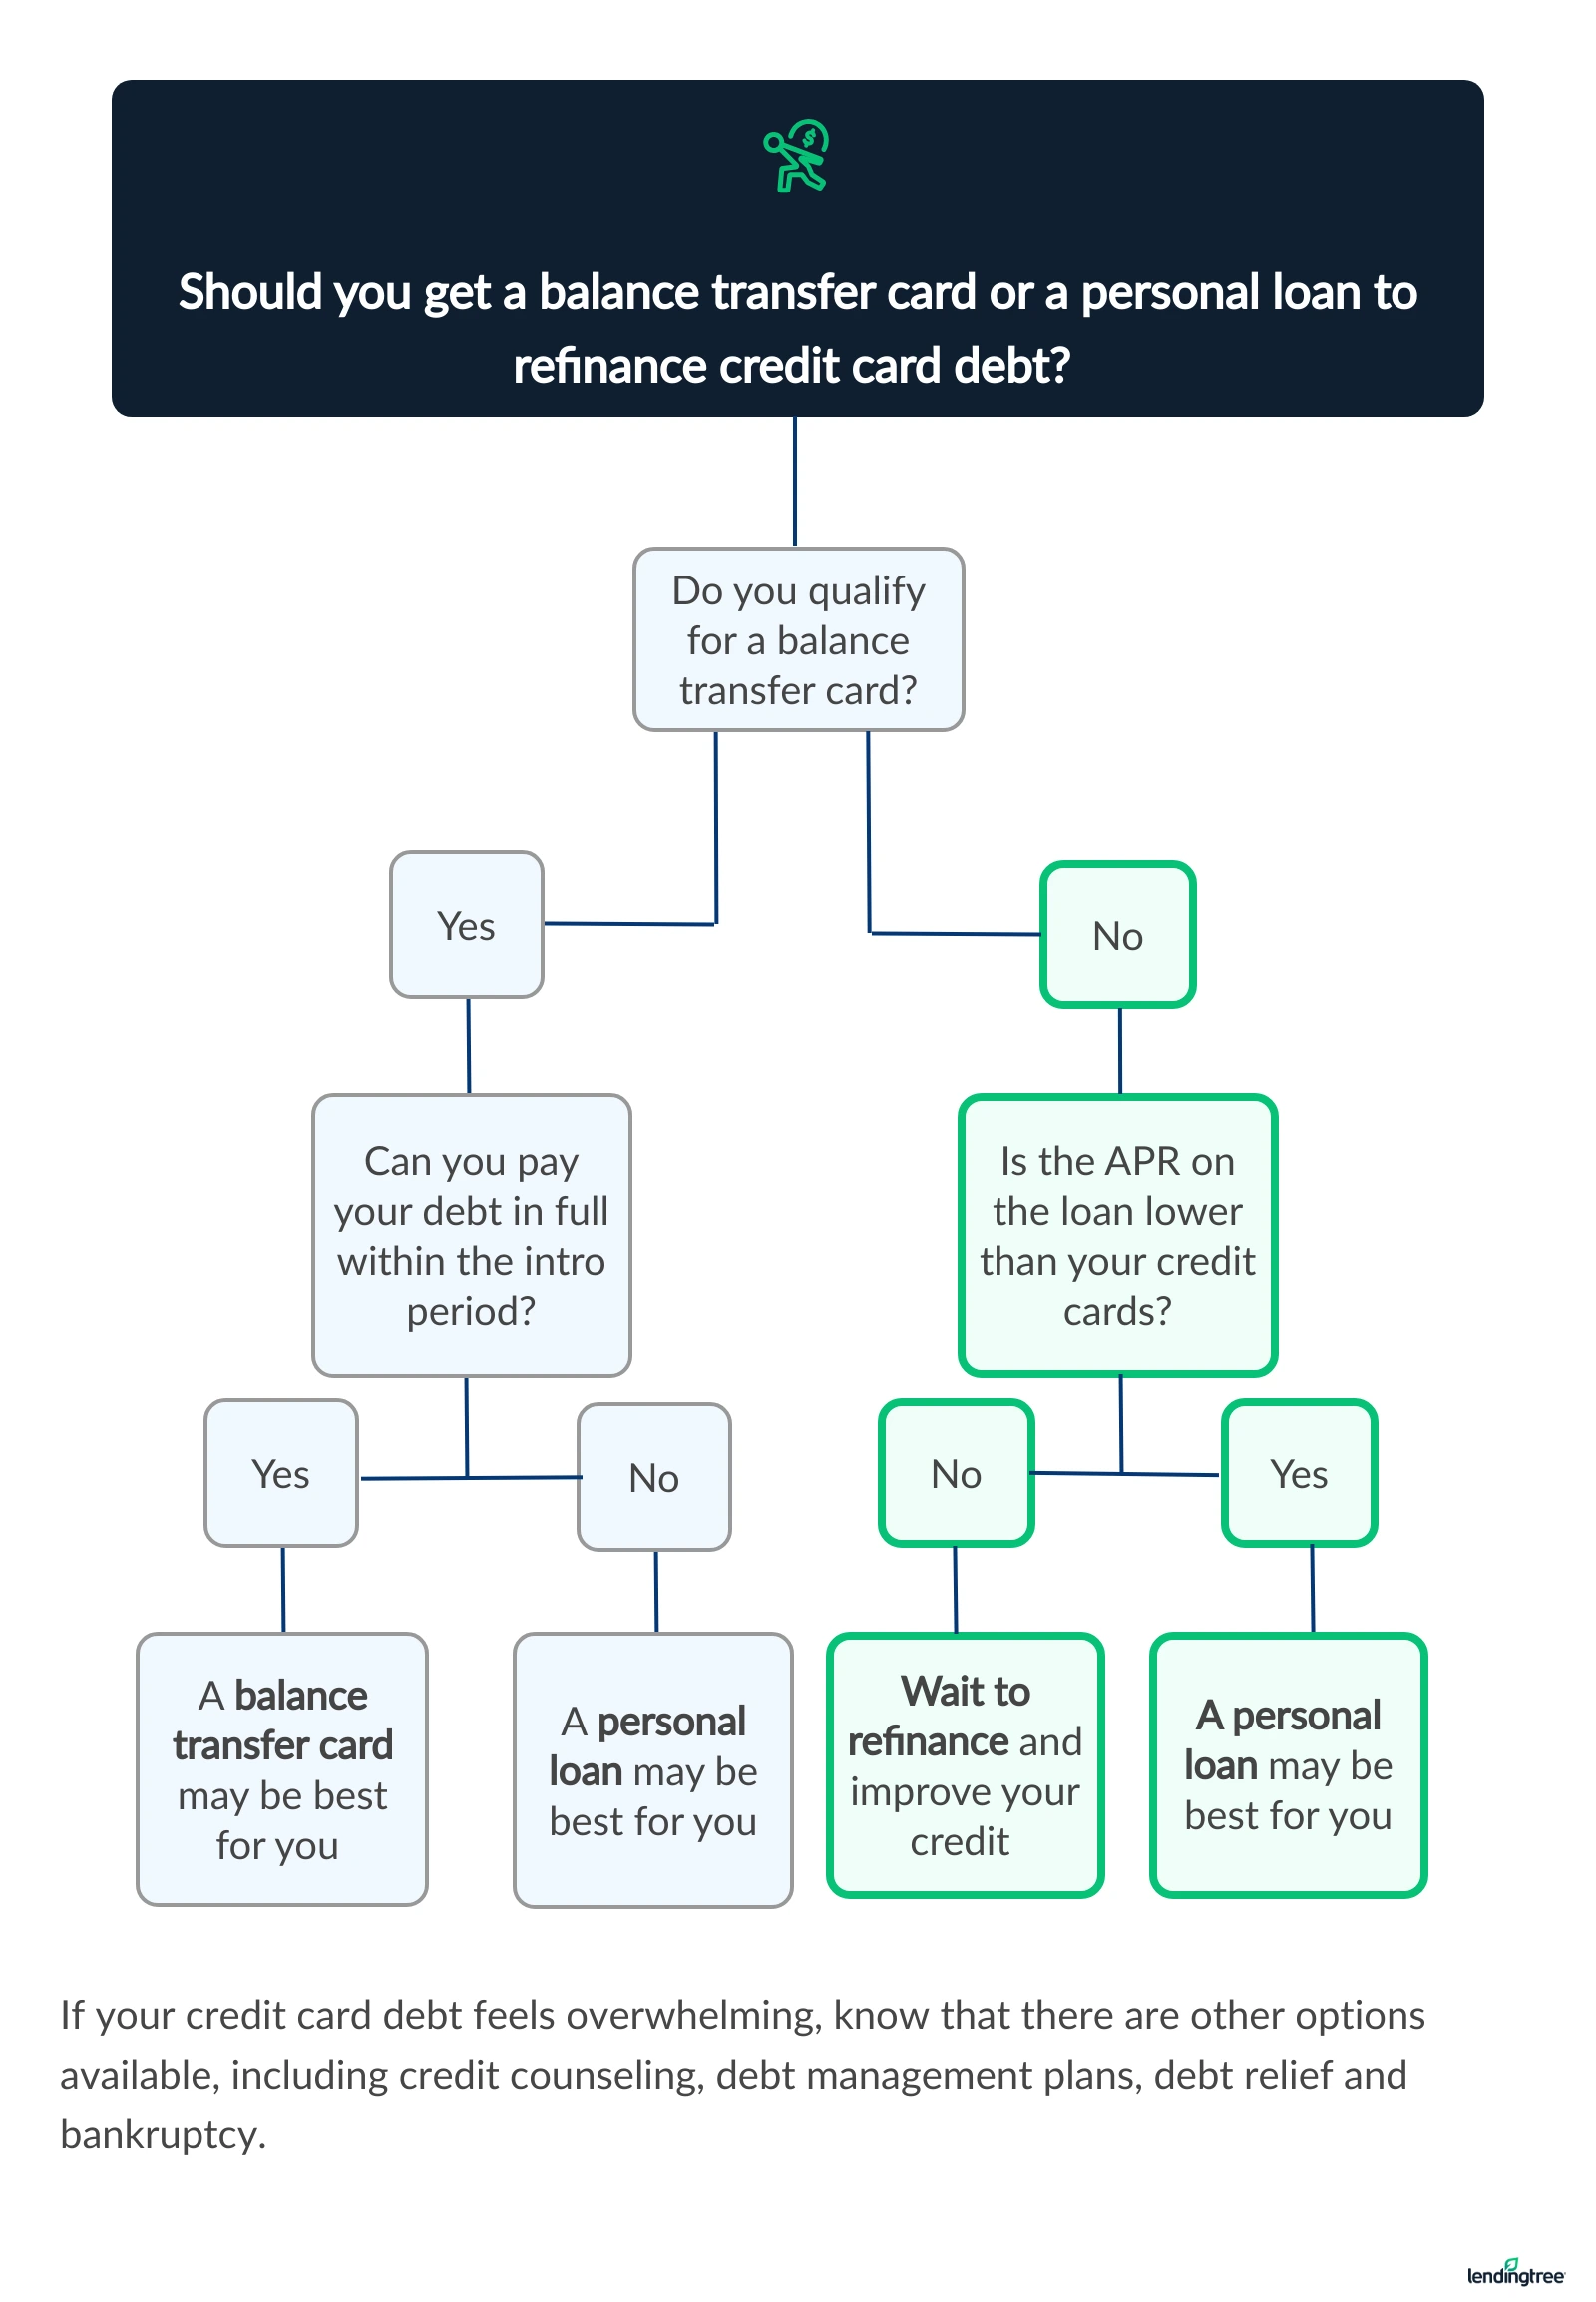
Steps to Lower Credit Card Debt in 2026
Smart Tips to Handle 2026 Financial Stress